25.2%
Banks sell a quarter of North Macedonia's life insurance
In Poland their share fell.
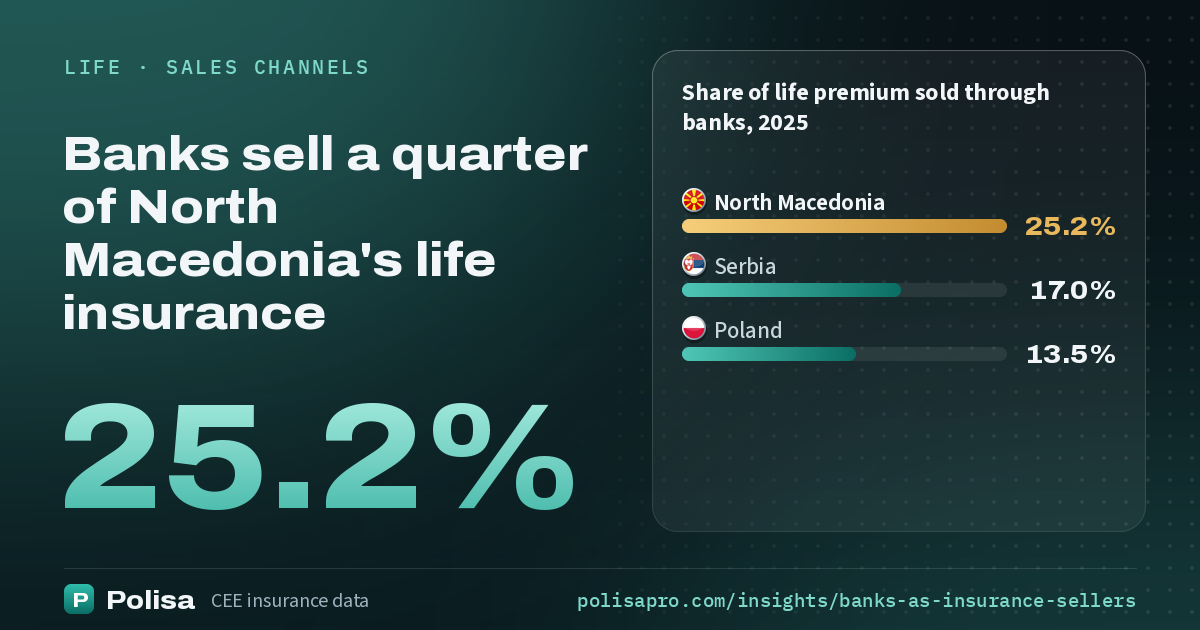
Three of the 18 markets publish premium by sales channel with banks as a channel of their own. From 2021 to 2025 the banks' share of life premium rose from 15.4% to 25.2% in North Macedonia and from 15.3% to 17.0% in Serbia, and fell from 18.6% to 13.5% in Poland. Banks sell little non-life insurance: 2.6% to 5.2% of it in 2025.
Show or hide lines
In 2025 banks sold €1.2bn of insurance in Poland, €91m in Serbia and €25m in North Macedonia: 5.7%, 5.6% and 8.7% of all premium. Most of it is life insurance.
North Macedonia's banks went furthest. They sold 25.2% of life premium in 2025, against 15.4% in 2021, and 5.2% of non-life premium (2.1%). The supervisor, ISA, counts eight banks that work as insurance agents, and writes that people who apply for a loan are more and more often sent by the bank to take out life cover for the term of the loan and insurance on the mortgaged property (annual report on the insurance market, 2025).
In Serbia the banks' share of life premium rose slowly, from 15.3% to 17.0%, while their non-life sales almost tripled from 2023 to 2025, from RSD 1.7bn to 4.9bn, mostly cover sold with loans, such as credit and financial loss insurance (NBS table T15).
Poland went the other way. Banks sold 18.6% of life premium in 2021 and 13.5% in 2025, and their premium fell from PLN 6.2bn to 5.1bn while the market grew by 31% in złoty. The share fell in 2022, the year KNF's product intervention on unit-linked policies took effect, and again in 2024 and 2025; in mid-2024 PKO Bank Polski stopped selling insurance with cash loans for a single premium and moved to monthly premiums. KNF also shows what banks earn: they were owed PLN 1.04bn in commission on PLN 5.08bn of premium in 2025 (20%), against PLN 1.33bn on PLN 5.43bn in 2024 (25%).
How the figures are counted: premium sold through banks over each market's premium, life and non-life apart, as each supervisor prints it; the totals are the market totals on the market pages. Poland's supervisor, KNF, counts banks that work as insurance agents; it changed the layout of its table in 2024, and the bank line is the same in both. Serbia's, NBS, counts written premium in non-life and invoiced premium in life, both without tax. North Macedonia's, ISA, counts the banks licensed as insurance agents. The other 15 markets publish no such series: some show intermediaries only in total, some only for some years. Each supervisor counts banks in its own way, so each market is best read over time rather than against the others.
Source: KNF, insurance market yearbooks 2021–2025, tables V.5 and V.12; NBS, table T15, total premium by sales channel, 2021–2025; ISA, annual reports on the state of the insurance market for 2021, 2023 and 2025; Polisa's calculation.
The numbers behind it
| Market | Sold through banks | 2021 | 2022 | 2023 | 2024 | 2025 |
|---|---|---|---|---|---|---|
| North Macedonia | Share of life premium | 15.4% | 20.9% | 23.2% | 26.2% | 25.2% |
| Share of non-life premium | 2.1% | 3.3% | 3.7% | 4.2% | 5.2% | |
| Serbia | Share of life premium | 15.3% | 15.1% | 15.9% | 16.8% | 17.0% |
| Share of non-life premium | 2.3% | 1.7% | 1.4% | 2.2% | 3.1% | |
| Poland | Share of life premium | 18.6% | 15.7% | 16.4% | 15.4% | 13.5% |
| Share of non-life premium | 4.5% | 3.2% | 3.0% | 2.9% | 2.6% |
More insights
Groupama and Talanx gained most ground since 2021
11 of 18At 2025 exchange rates Groupama's share of the 18 markets' premium rose from 1.7% in 2021 to 3.1%, and Talanx's from 5.9% to 6.3% although it sold its Hungarian insurers; VIG's rise to 16.3% came mostly from buying Aegon's. 2.9% of the 2021 premium is now in another group, foreign groups still write 71.5%, and insurers owned by banks 10.2% of life premium. Scroll through who gained, what changed hands, concentration, owners and banks.
Life insurance lost ground in 13 of the 18 markets
13 of 18Life insurance was 30.6% of the 18 markets' premium in 2021 and 26.1% in 2025. At 2025 exchange rates life premium grew 4.2% a year and non-life 10.0%; after inflation life premium fell in eleven markets, and in Latvia and Croatia it fell even before it.
Premium in the 18 markets grew 41.2% in euros since 2021
+37.8%The 18 markets wrote €40.28bn of premium in 2021 and €56.87bn in 2025, 41.2% more in euros. At 2025 exchange rates the rise is 37.8%: the złoty's gain against the euro added 4.0 points and the koruna's 0.8, while the forint's fall took 1.3 off.
Pages behind it
When the figures change
Every data update is listed with its date, newest first: new figures, corrections and what they changed.
What changedCiteCite this pageThe reference in APA style and as BibTeX, each with a copy button, and the terms of reuse
Polisa compiles the figures; the original sources are named on this page and on the method page.
Polisa. (2026). Banks now sell a quarter of North Macedonia's life insurance, while in Poland their share fell [Data version 2026-11-21.b74841]. Retrieved November 21, 2026, from https://polisapro.com/insights/banks-as-insurance-sellers
BibTeXShow entry
@misc{polisa_insights_banks_as_insurance_sellers_2026,
  author       = {{Polisa}},
  title        = {Banks now sell a quarter of North Macedonia's life insurance, while in Poland their share fell},
  year         = {2026},
  version      = {2026-11-21.b74841},
  howpublished = {\url{https://polisapro.com/insights/banks-as-insurance-sellers}},
  note         = {Accessed 21 November 2026}
}
Reuse: Polisa's compilation CC BY 4.0 · source data under each publisher's terms, see Method.