Poland
Growth
Amounts are always in euros: this changes how growth is measured, nothing else.
How growth is measured →This page is also available in Polish.
Latest news6 Nov 2026: Senate passes law widening KUKE's cover to defence and energy, President to sign next All news (21) →
Coverage The insurers shown write 99.0% of the market. KNF's total also counts the reinsurer PTR, which is not shown. Branches of EU insurers and cross-border business report nothing to KNF; EIOPA data put their direct premium at €1.65bn or more in 2025. EIOPA does not endorse this publication and is in no way liable for copyright or other rights infringements, nor for the consequences of using its data. Source.
Market share by insurer
Latest quarter: H1 2026
Premium written H1 2026, year to date: €11.01bn, +6.6% against H1 2025 in local currency. Share change in percentage points against the same period a year earlier.
Largest insurers, H1 2026
Premium year to date and growth; the bar is the share, its change in points under it.

Gains and losses in share
Change in share against H1 2025, in percentage points; an insurer with no premium now has lost its whole share.

- PZU · 1 Jun 2026: PZU–Pekao merger: minister says work continues, deadline now end-2027
- PKO Ubezpieczenia · 2 Jul 2026: KNF opens penalty case against PKO TU over motor TPL pricing
All figures
| Insurer | H1 2026 €m | Share | Δ pp | H1 2025 €m | Growth |
|---|---|---|---|---|---|
| PZU | 2,110.4 | 19.2% | −0.7 | 2,058.0 | +2.8% |
| Warta | 1,591.0 | 14.4% | −0.6 | 1,557.5 | +2.4% |
| PZU Życie | 1,287.8 | 11.7% | −0.6 | 1,269.3 | +1.7% |
| ERGO Hestia | 1,265.8 | 11.5% | +0.1 | 1,185.6 | +7.1% |
| UNIQA | 646.5 | 5.9% | −0.0 | 608.6 | +6.5% |
| Compensa | 539.5 | 4.9% | +0.1 | 492.6 | +9.8% |
| Allianz Życie | 402.7 | 3.7% | +0.4 | 336.0 | +20.2% |
| Generali | 324.7 | 2.9% | −0.3 | 331.5 | −1.8% |
| Allianz | 291.4 | 2.6% | −0.2 | 291.0 | +0.4% |
| Nationale-Nederlanden | 279.9 | 2.5% | −0.1 | 274.5 | +2.3% |
| Warta Życie | 235.5 | 2.1% | +0.1 | 209.7 | +12.6% |
| Vienna Life | 235.3 | 2.1% | −0.0 | 223.2 | +5.7% |
| InterRisk | 228.3 | 2.1% | −0.1 | 220.5 | +3.9% |
| UNIQA Życie | 133.3 | 1.2% | +0.0 | 123.0 | +8.7% |
| TUW PZUW | 132.6 | 1.2% | +0.1 | 117.6 | +13.1% |
| Generali Życie | 121.1 | 1.1% | −0.0 | 116.8 | +4.1% |
| Link4 | 117.3 | 1.1% | −0.1 | 125.0 | −5.9% |
| PKO Ubezpieczenia | 98.3 | 0.9% | +0.2 | 70.9 | +39.1% |
| Unum Życie | 97.9 | 0.9% | +0.0 | 87.2 | +12.6% |
| ERGO Hestia Życie | 91.7 | 0.8% | +0.0 | 83.3 | +10.4% |
| Credit Agricole Życie | 87.4 | 0.8% | +0.3 | 55.0 | +59.5% |
| PKO Życie | 84.9 | 0.8% | +0.7 | 10.9 | +683.6% |
| TUW TUW | 80.2 | 0.7% | −0.1 | 82.1 | −2.0% |
| TUZ Ubezpieczenia | 64.5 | 0.6% | +0.1 | 51.5 | +25.6% |
| Agro Ubezpieczenia | 53.7 | 0.5% | +0.0 | 50.4 | +6.8% |
| Erste Allianz Życie | 49.0 | 0.4% | +0.1 | 33.4 | +47.3% |
| Cardif Polska | 42.1 | 0.4% | +0.0 | 37.1 | +14.0% |
| Europa | 37.1 | 0.3% | +0.2 | 18.1 | +105.2% |
| Inter Polska | 35.1 | 0.3% | +0.0 | 31.9 | +10.1% |
| TU Zdrowie | 32.1 | 0.3% | +0.1 | 24.4 | +31.9% |
| Nationale-Nederlanden Ubezpieczenia | 29.4 | 0.3% | +0.0 | 26.5 | +11.2% |
| Credit Agricole Ubezpieczenia | 23.0 | 0.2% | +0.1 | 12.1 | +90.9% |
| KUKE | 22.9 | 0.2% | +0.0 | 19.7 | +16.9% |
| Saltus | 22.8 | 0.2% | +0.0 | 16.6 | +37.7% |
| TUW Cuprum | 22.2 | 0.2% | −0.0 | 21.4 | +3.6% |
| Europa Życie | 20.0 | 0.2% | +0.6 | -42.7 | — |
| Erste Allianz | 19.8 | 0.2% | +0.0 | 17.6 | +12.4% |
| Signal Iduna | 14.1 | 0.1% | −0.1 | 19.7 | −28.5% |
| Saltus Życie | 12.1 | 0.1% | −0.0 | 16.1 | −24.9% |
| Pocztowe Życie | 10.2 | 0.1% | +0.0 | 9.0 | +13.0% |
| Signal Iduna Życie | 6.8 | 0.1% | −0.0 | 6.5 | +4.2% |
| Open Life | 3.8 | 0.0% | −0.0 | 4.7 | −17.6% |
| Inter Życie | 3.2 | 0.0% | +0.0 | 2.9 | +8.8% |
| Partner | 2.7 | 0.0% | +0.0 | 0.9 | +218.1% |
| Rejent Life | 2.4 | 0.0% | −0.0 | 2.4 | +1.4% |
| Lux Med Ubezpieczenia | 0.2 | 0.0% | new | — | — |
| Allianz Trade (Euler Hermes) no premium in H1 2026 | — | — | −0.5 | 50.8 | — |
| Market | 11,012.9 | 100% | 10,360.8 | +6.6% |
Each insurer's figures: All insurers, growth and latest quarter → · Full-year outlook →
What's happening in Poland
The latest news on the market's insurers and their supervisor, newest first: facts in Polisa's own words, each with its source.
- LawSenate passes law widening KUKE's cover to defence and energy, President to sign next
The Senate passed without changes the amendment letting state export credit insurer KUKE back defence, dual-use and energy projects and take stakes in similar foreign institutions. It now needs the President's signature.
KUKESource: Gazeta Ubezpieczeniowa - PricesCheapest motor TPL offers rise again in October, median up 2.8% to PLN 671
The Rankomat.pl median of the cheapest motor TPL offers rose by PLN 18 in October 2026 to PLN 671, 1.7% above a year earlier. Rankomat.pl says rising claim costs are the main driver.
Source: Rankomat.pl - DealQuercus agrees to buy 49% of Open Life from bankrupt Open Finance
A Quercus TFI subsidiary signed a conditional deal with the bankruptcy trustee of Open Finance to buy 49% of life insurer Open Life for just under PLN 14.8m. Closing needs, among other things, no objection from KNF.
Open LifeSource: Biznesradar - SupervisorKNF cuts Compensa's fine for underpriced motor TPL to PLN 5m
On reconsideration, KNF replaced its April fine of PLN 8.5m with PLN 5m for setting motor TPL premiums in 2022–2024 too low to cover obligations and costs. KNF cites a changed basis for the maximum fine; Compensa can still appeal.
CompensaSource: KNF
17 earlier
- PricesCheapest motor TPL offers post the biggest monthly rise in about 2.5 years
The Rankomat.pl median of the cheapest motor TPL offers rose by PLN 29 in September 2026 to PLN 653. According to Auto Świat, insurers point to higher repair and parts costs.
Source: Auto Świat (Rankomat.pl data) - LawGovernment adopts bill widening KUKE's cover to defence and energy
The Council of Ministers adopted a draft amendment letting the state export credit insurer KUKE insure defence and security investments and energy projects, and take on part of other insurers' risk where market cover is lacking.
KUKESource: XYZ.pl - ResultsUFG: motor TPL claims paid rose to PLN 6.36bn in the first half of 2026
Insurance Guarantee Fund data show motor TPL claims paid of PLN 6.36bn by end-June 2026, against PLN 5.83bn a year earlier. Motor own-damage (AC) claims paid rose to PLN 4.92bn from PLN 4.37bn.
Source: Strefa Inwestorów (UFG data) - DealKNF unanimously raised no objection to PZU absorbing its subsidiary LINK4.Link4Source: KNF (communiqué of 28 Aug 2026); PAP Biznes (28 Aug 2026); XYZ.pl (23 Oct 2026)
- ResultsPIU: market premium up 7.1% to PLN 47.3bn in the first half of 2026
Life premium rose 12.5% to PLN 13.6bn and non-life 5.0% to PLN 33.7bn. The average motor TPL premium held at PLN 548, and the sector's net profit grew about 5% to PLN 8.7bn.
Source: PIU via BANK.pl - ResultsPZU's first-half 2026 net profit falls 6.8% to PLN 3.0bn
PZU Group's insurance revenue rose to PLN 15.65bn from PLN 15.23bn, but net profit attributable to shareholders fell to PLN 3.01bn from PLN 3.23bn. The combined ratio in Polish non-life was 87.9%, close to a year earlier.
PZUSource: BANK.pl - LawPresident signs reform of state-subsidised crop insurance
The amendment to the act on insurance of crops and farm animals ends the link between premium subsidies and soil class and brings in a reductive deductible in place of the integral one.
Source: Podatki.biz - SupervisorKNF opens penalty case against PKO TU over motor TPL pricing
KNF started proceedings that may end in a fine for PKO Towarzystwo Ubezpieczeń, suspecting it set motor TPL premiums in 2023–2025 too low to cover its obligations and costs. No penalty has been decided yet.
PKO UbezpieczeniaSource: KNF - DealSALTUS TU Życie announced plans to take over the Polish business of the French Prévoir group, subject to supervisory approval.Source: BANK.pl
- DealPZU–Pekao merger: minister says work continues, deadline now end-2027
State Assets Minister Wojciech Balczun said work on the PZU–Pekao deal will continue, with several scenarios studied. The parties aim to finish by end-2027; the deal lapses if the needed laws are not published by end-2026.
PZUSource: Bankier.pl (PAP) - SupervisorKNF warns of a 'low-price trap' after the sector earned PLN 12.5bn in 2025
KNF deputy chair Krystian Wiercioch told the PIU congress that underpriced cover leads to refused or cut claims. All insurers met capital requirements in 2025 (sector ratio 233%); KNF will benchmark motor TPL claim speed.
Source: BANK.pl (PAP Biznes) - CompanyThe bancassurance life insurer was renamed Erste Allianz TU na Życie when Santander Bank Polska became Erste Bank Polska.Erste Allianz ŻycieSource: Compabase (KRS data)
- ResultsPIU: insurers wrote PLN 90.6bn of premium in 2025, profit above PLN 12.5bn
Life premium rose 5.2% to PLN 24.8bn and non-life 6.0% to PLN 65.8bn. Claims and benefits paid reached PLN 53.8bn, and the average motor TPL premium rose 2.7% to PLN 553.
Source: PIU via BANK.pl - DealErste Group completed its purchase of control of Santander Bank Polska, making it the new partner of Allianz in the bank's two insurers.Erste Allianz ŻycieSource: Erste Group press release
Five-year trend
Premium
Market share of the five largest
Lines in Poland
All figures
Motor TPL, FY 2025: average premium €145 per policy, 3.5 claims per 100 policies, average claim €2,868. Prices in every market on the Motor TPL page →
Claims paid in Poland
Insurers paid €12.11bn to their customers in FY 2025, +6.4% on FY 2024 in PLN: €60 for every €100 of premium. Non-life claims were €7.99bn; life insurance benefits €4.12bn.
Premium and claims paid, FY 2021–2025
PremiumClaims paid% claims paid per €100 of premium
Claims paid by line, FY 2025
Claims and benefits paid in the year by the insurers KNF supervises, on their direct business in Poland, before reinsurance; life includes maturities and surrenders. Source: KNF statistical tables. Cash paid in the year, not the claims incurred that the combined ratios on this page are built from. Claims across all markets →
Reinsurance in Poland
Share of non-life premium ceded, by line
Largest cedents
All figures
Capital cover across the market
Groups present
Each group's share of this market, its companies here, and where else it operates.
Profit and capital
Net profit by year
All figures
Each insurer's profit, return on equity and ratios: All insurers, solvency and profit →
Questions about Poland
Short answers from the figures on this page.
How big is the Poland insurance market?
Insurers in Poland wrote €21.2bn of premium in FY 2025, +5.7% on FY 2024 in PLN. That is 2.3% of GDP and €580 per person.
Who is the largest insurer in Poland?
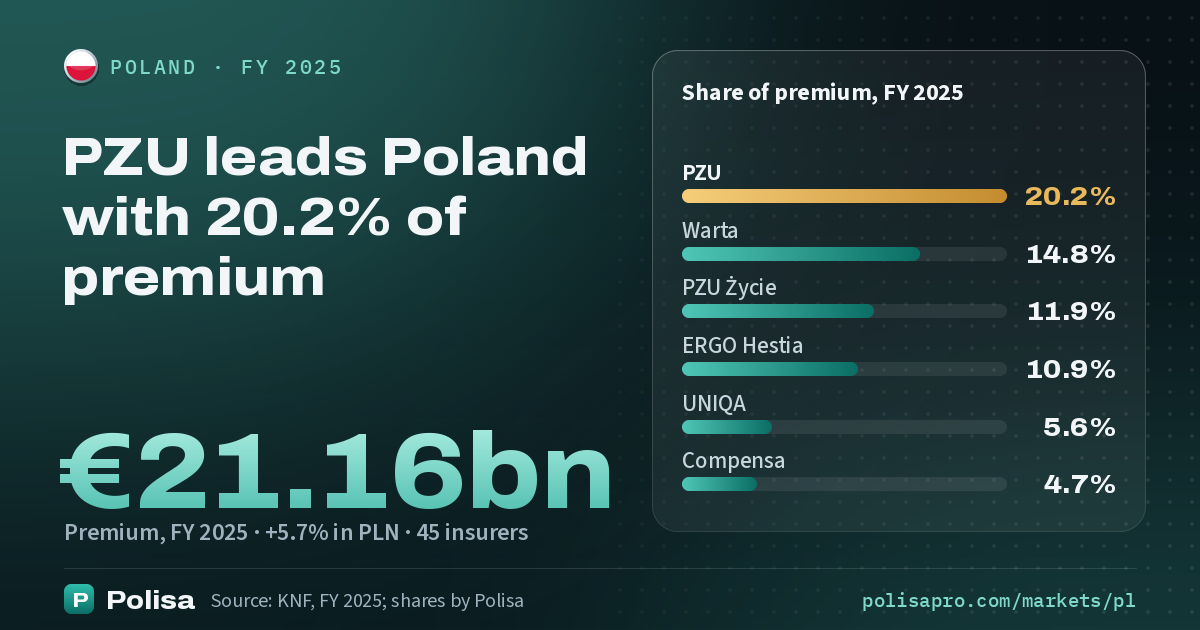
PZU is the largest insurer in Poland with 20.2% of premium (€4.27bn) in FY 2025, ahead of Warta (14.8%) and PZU Życie (11.9%); the three largest write 47% of the market.
How many insurance companies are there in Poland?
45 insurers wrote premium in Poland in FY 2025: 26 non-life and 19 life.
Which insurance groups are present in Poland?
Polisa records 17 insurance groups in Poland in FY 2025; the largest by premium are PZU 35.0%, Talanx 16.9%, ERGO 11.7%, VIG 8.9%. Insurers with no group (independent or not in a group) write 2.1% of the premium.
What is the largest line of business in Poland?
Life insurance is the largest line in Poland with 22.6% of premium (€4.69bn) in FY 2025, then motor TPL with 21.4%.
How well capitalised are the insurers in Poland?
The median SCR ratio of the insurers in Poland was 210% at 31 December 2025: the typical insurer held 2.1 times the capital Solvency II requires. 43 of the 45 insurers publish it.
RegulationRule changes7 rule changes that reach insurers in Poland, with their dates
- Solvency II review · Applies from 30 January 2027
- The natural catastrophe protection gap · Framework presented 27 October 2026; first insurance measures due by the end of 2027
- Motor liability: prices move in different directions · Romania's price cap ended 1 July 2025
- AI Act: pricing rules for life and health delayed · High-risk rules from 2 December 2027
- Retail Investment Strategy: value for money · European Parliament vote scheduled for 12 November 2026; the rules apply 30 months after publication
- Recovery and resolution of insurers · Applies from 30 January 2027
- DORA: digital operational resilience · In application since 17 January 2025
Spotted a wrong figure? Tell us and include the source.
All insurers
ExcelDownload CSVLicence| Insurer | Premium | Share |
|---|---|---|
| PZU | 4,267.4 | 20.2% |
| Warta | 3,122.6 | 14.8% |
| PZU Życie | 2,525.4 | 11.9% |
| ERGO Hestia | 2,307.5 | 10.9% |
| UNIQA | 1,187.1 | 5.6% |
| Compensa | 984.6 | 4.7% |
| Generali | 697.6 | 3.3% |
| Allianz Życie | 695.6 | 3.3% |
| Allianz | 568.8 | 2.7% |
| Nationale-Nederlanden | 556.8 | 2.6% |
| InterRisk | 452.2 | 2.1% |
| Vienna Life | 445.0 | 2.1% |
| Warta Życie | 430.3 | 2.0% |
| TUW PZUW | 367.4 | 1.7% |
| UNIQA Życie | 250.6 | 1.2% |
| Generali Życie | 237.5 | 1.1% |
| Link4 | 235.8 | 1.1% |
| Unum Życie | 181.2 | 0.9% |
| ERGO Hestia Życie | 171.4 | 0.8% |
| TUW TUW | 169.3 | 0.8% |
| PKO Ubezpieczenia | 149.1 | 0.7% |
| Agro Ubezpieczenia | 142.9 | 0.7% |
| Credit Agricole Życie | 120.1 | 0.6% |
| TUZ Ubezpieczenia | 119.1 | 0.6% |
| Allianz Trade (Euler Hermes) | 98.5 | 0.5% |
| Cardif Polska | 77.5 | 0.4% |
| Erste Allianz Życie | 75.3 | 0.4% |
| Inter Polska | 64.5 | 0.3% |
| Europa | 57.0 | 0.3% |
| TU Zdrowie | 53.4 | 0.3% |
| Nationale-Nederlanden Ubezpieczenia | 48.8 | 0.2% |
| KUKE | 46.4 | 0.2% |
| PKO Życie | 41.7 | 0.2% |
| Saltus | 37.4 | 0.2% |
| Signal Iduna | 36.4 | 0.2% |
| Erste Allianz | 35.3 | 0.2% |
| Saltus Życie | 30.8 | 0.1% |
| Credit Agricole Ubezpieczenia | 27.6 | 0.1% |
| TUW Cuprum | 23.1 | 0.1% |
| Pocztowe Życie | 18.8 | 0.1% |
| Signal Iduna Życie | 13.2 | 0.1% |
| Open Life | 8.8 | 0.0% |
| Inter Życie | 5.8 | 0.0% |
| Rejent Life | 4.8 | 0.0% |
| Partner | 2.4 | 0.0% |
| Europa Życie | -36.6 | — |
CiteCite this pageThe reference in APA style and as BibTeX, each with a copy button, and the terms of reuse
Polisa compiles the figures; the original sources are named on this page and on the method page.
Polisa. (2026). Poland insurance market: market shares, lines, solvency and claims [Data version 2026-11-11.13378f]. Retrieved November 11, 2026, from https://polisapro.com/markets/pl
BibTeXShow entry
@misc{polisa_markets_pl_2026,
  author       = {{Polisa}},
  title        = {Poland insurance market: market shares, lines, solvency and claims},
  year         = {2026},
  version      = {2026-11-11.13378f},
  howpublished = {\url{https://polisapro.com/markets/pl}},
  note         = {Accessed 11 November 2026}
}
Reuse: Polisa's compilation CC BY 4.0 · source data: KNF (open data, credit KNF), insurers' SFCRs (public disclosures, linked).