
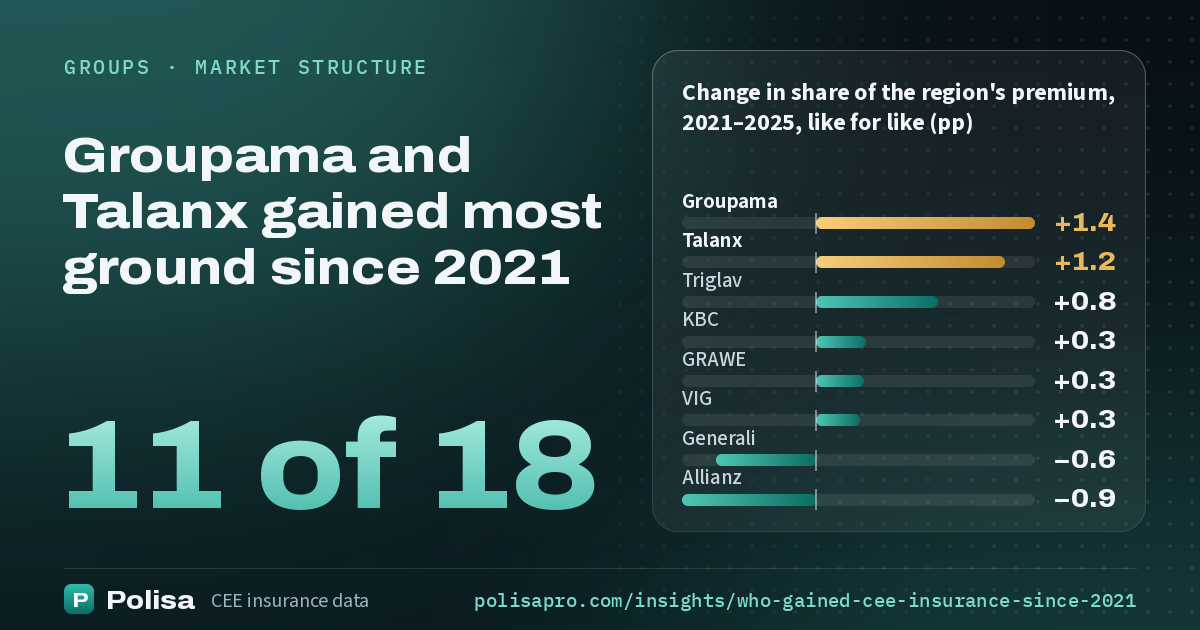
How the figures are counted: premium is each market's written premium as on the market pages, converted at 2025's exchange rates in both years, as in the insight on growth at constant exchange rates, so currencies do not move the shares. A group counts the insurers it holds in each year. Like for like sets a group's insurers of 2025 against the same insurers in 2021, an insurer merged into another counting with it, so that what a group bought or sold is apart from its own growth. The three largest insurers are counted by company, as on the market pages.
Owners are Polisa's owner list: for each group the head office of its parent and whether it is a bank, from the groups' own reports and investor pages, checked on 18 November 2026; a group in one market is local or foreign as its insurers' reports say. A branch counts with its foreign insurer. Slovenia's 2025 figures include the €697m Triglav wrote in Italy. Changes of group are those on the deals page, from the buyers' and supervisors' announcements.
Source: premium by insurer from each market's supervisor or insurance association, as on the market pages; owners from the groups' and insurers' reports; deals from Polisa's deals page; Polisa's calculation.
The numbers behind it
| Market | Premium | Gained most | 2021 elsewhere | Top three | Insurers | Foreign | Banks, life |
|---|---|---|---|---|---|---|---|
| Poland | €21.16bn | Talanx +4.0 | 1.9% | 43% → 47% | 54 → 45 | 61% | 4% |
| Czechia | €8.31bn | KBC +1.2 | 0.0% | 59% → 57% | 22 → 22 | 94% | 25% |
| Hungary | €5.13bn | Groupama +3.2 | 20.7% | 40% → 41% | 25 → 25 | 87% | 5% |
| Romania | €4.34bn | Groupama +11.1 | 29.5% | 43% → 54% | 27 → 25 | 96% | 11% |
| Slovenia | €3.38bn | Triglav +13.3 | 0.2% | 65% → 83% | 16 → 15 | 22% | — |
| Slovakia | €3.20bn | Generali +1.7 | 0.5% | 63% → 63% | 14 → 13 | 100% | 7% |
| Bulgaria | €2.68bn | DallBogg +2.1 | 1.3% | 30% → 30% | 33 → 36 | 50% | 29% |
| Croatia | €2.11bn | Agram +1.7 | 0.5% | 48% → 52% | 15 → 14 | 43% | — |
| Lithuania | €1.73bn | VIG +3.4 | 1.3% | 41% → 45% | 19 → 18 | 98% | 44% |
| Serbia | €1.63bn | Globos osiguranje +1.7 | 0.0% | 58% → 55% | 16 → 16 | 64% | 6% |
| Latvia | €850m | Balcia Insurance +3.8 | 0.5% | 42% → 46% | 16 → 17 | 92% | 53% |
| Estonia | €680m | LHV +4.9 | 1.7% | 44% → 44% | 17 → 18 | 87% | 74% |
| Bosnia and Herzegovina | €600m | Agram +2.0 | 0.0% | 26% → 32% | 25 → 23 | 59% | — |
| North Macedonia | €291m | GRAWE +2.3 | 10.9% | 30% → 35% | 16 → 17 | 94% | — |
| Albania | €277m | Albsig +2.6 | 27.6% | 53% → 53% | 12 → 13 | 20% | — |
| Kosovo* | €179m | SIGAL +2.2 | 17.3% | 34% → 38% | 13 → 12 | 51% | — |
| Moldova | €171m | Intact Asigurări Generale +3.4 | 0.8% | 48% → 45% | 10 → 9 | 30% | — |
| Montenegro | €148m | VIG +3.1 | 0.0% | 61% → 61% | 9 → 9 | 100% | — |
Premium written in 2025. Gained most: the group (or insurer outside any group) whose share of the market rose most from 2021 to 2025, its insurers of 2025 against the same insurers in 2021, in points. 2021 elsewhere: the share of the market's 2021 premium written by insurers that are in another group in 2025, or that failed. Top three: the three largest insurers' share. Foreign: the share of groups based outside the market and of branches of foreign insurers. Banks, life: the share of the market's life premium written by insurers owned by a bank or a banking group.
More insights
Five groups write 56% of the region's insurance premium
56%The 18 markets Polisa covers wrote €56.87bn of premium in 2025, and VIG, PZU, Generali, Allianz and Talanx wrote 56% of it. VIG is the only group with an insurer in every market and leads six of them. Scroll through who leads each market, how much the leader holds and the 57 deals since 2021, 33 of them between different owners.
Two groups write half of Baltic insurance, and ERGO is now third
49%VIG and PZU wrote 49% of premium in Lithuania, Latvia and Estonia in 2025. ERGO's purchase of Gjensidige's Baltic company moves it past Swedbank into third place.
Who took Romania's market after City and Euroins failed
22.5%City Insurance and Euroins held 28% of Romanian premium in 2021. Both lost their licences; Groupama doubled its share to 22.5%, and Generali and Asirom gained 3.8 and 3.6 points.
Pages behind it
When the figures change
Every data update is listed with its date, newest first: new figures, corrections and what they changed.
What changedCiteCite this pageThe reference in APA style and as BibTeX, each with a copy button, and the terms of reuse
Polisa compiles the figures; the original sources are named on this page and on the method page.
Polisa. (2026). Groupama and Talanx gained most ground since 2021, and the top three insurers gained in 11 of 18 markets [Data version 2026-11-21.b74841]. Retrieved November 21, 2026, from https://polisapro.com/insights/who-gained-cee-insurance-since-2021
BibTeXShow entry
@misc{polisa_insights_who_gained_cee_insurance_since_2021_2026,
  author       = {{Polisa}},
  title        = {Groupama and Talanx gained most ground since 2021, and the top three insurers gained in 11 of 18 markets},
  year         = {2026},
  version      = {2026-11-21.b74841},
  howpublished = {\url{https://polisapro.com/insights/who-gained-cee-insurance-since-2021}},
  note         = {Accessed 21 November 2026}
}
Reuse: Polisa's compilation CC BY 4.0 · source data under each publisher's terms, see Method.