40 of 64
40 of 64 large non-life insurers in the EU markets made an underwriting profit after reinsurance in each of the last five years
Among insurers in the eleven Solvency II markets with at least €50m of non-life earned premium in every year from 2021 to 2025, 40 kept their combined ratio after reinsurance below 100% each year. All of them in Czechia, Bulgaria, Slovenia and Latvia did; in Slovakia, one of six.
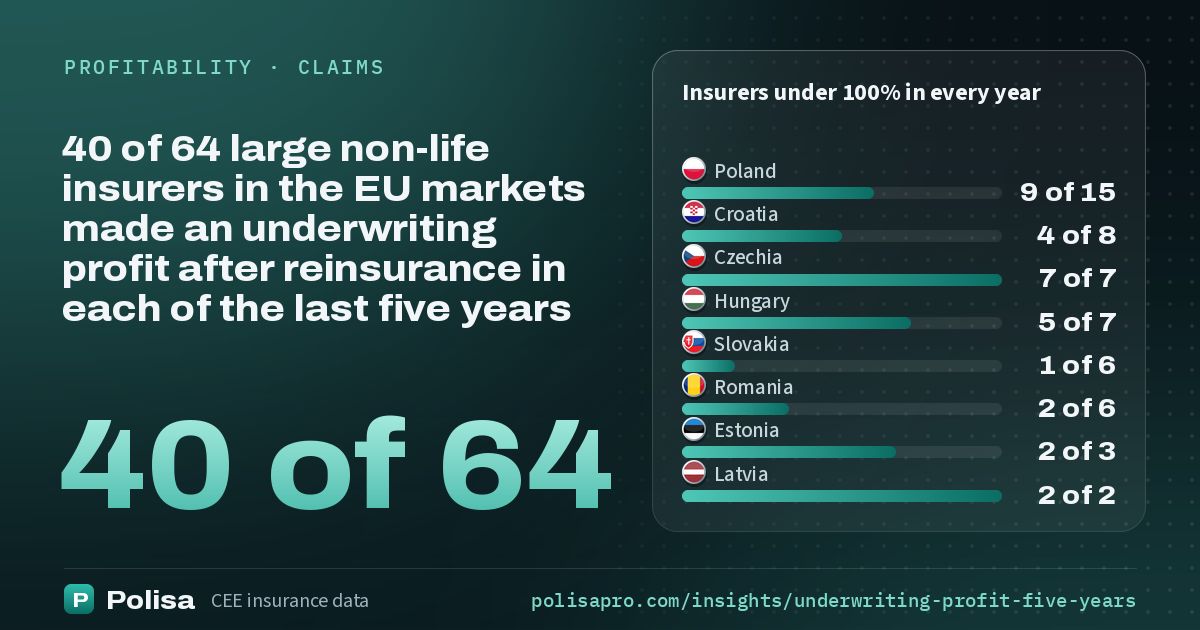
A combined ratio after reinsurance below 100% means that claims, net of what reinsurers paid, and expenses took less than the premium the insurer kept, before investment income. Of 64 insurers in the eleven Solvency II markets with at least €50m of non-life earned premium and figures after reinsurance in each of the five years, 40 stayed below 100% every year: 9 of 15 in Poland, 4 of 8 in Croatia, 5 of 7 in Hungary, and all of them in Czechia, Bulgaria, Slovenia and Latvia.
Of the 24 exceptions, 10 had a single year at or above 100%: three in 2021, four in 2023, two in 2024 and one in 2025. Triglav osiguranje in Croatia (2021, 2022, 2023, 2024 and 2025), UNIQA osiguranje in Croatia (2023 and 2025), Wiener osiguranje VIG in Croatia (2021, 2022, 2023 and 2024), Link4 in Poland (2023, 2024 and 2025), TUW TUW in Poland (2021, 2022, 2023, 2024 and 2025), Agro Ubezpieczenia in Poland (2024 and 2025), Europa in Poland (2024 and 2025), Omniasig in Romania (2021 and 2022), Asirom in Romania (2021, 2022 and 2025), UNIQA in Romania (2021, 2022 and 2023), Union VIG in Hungary (2023 and 2024), K&H in Hungary (2023 and 2024), Compensa VIG in Lithuania (2021, 2022 and 2023) and Gjensidige in Lithuania (2021 and 2022) were above 100% in more than one year. The table below lists every exception with its ratio for each year. Large insurers with a year missing are not counted, such as Groupama in Hungary, Euroins in Bulgaria, UNIQA (branch) in Slovakia and GRAWE in Romania.
Ratios are after reinsurance, as on the market pages: net claims and expenses over net earned premium, from S.05.01 in each insurer's SFCR, followed under the insurer's current name; each insurer's lines under €1m of earned premium are left out, and so is an insurer without figures after reinsurance in any of the years, or a life insurer, whose page shows no non-life ratio.
The numbers behind it
More insights
Underwriting made money in 17 of 18 markets in 2025, and Poland took 48% of the profit
17 of 18Claims and costs took less than the non-life premium after reinsurance in 17 of the 18 markets in 2025. The region's non-life insurers earned €1.88bn on underwriting and €2.01bn on investments, and insurers reported €5.14bn of net profit, 48% of it in Poland. Scroll through the combined ratio, investments, returns on equity, profit and five years of results.
Motor is 53% of non-life premium in the 18 markets, and over half in 12 of them
53%Motor liability and casco brought in €22.78bn of the €43.01bn the 18 markets wrote in non-life lines in 2025, which include the accident and health cover life insurers sell. Scroll through where motor matters most, claims that rise faster than premiums, what a policy costs, how prices moved and Romania after City and Euroins.
Hungarian insurers earn the highest return on equity in the region, 24%, Croatian insurers about 7%
24.4%Hungarian insurers returned 24.4% on average equity in 2025, Czech insurers 22.0% and Romanian insurers 20.1%. Polish insurers earned 19.2%, up from 10.4% in 2021. In Croatia the return has stayed between 6% and 8% in every year since 2021.
Pages behind it
When the figures change
Every data update is listed with its date, newest first: new figures, corrections and what they changed.
What changedCiteCite this pageThe reference in APA style and as BibTeX, each with a copy button, and the terms of reuse
Polisa compiles the figures; the original sources are named on this page and on the method page.
Polisa. (2026). 40 of 64 large non-life insurers in the EU markets made an underwriting profit after reinsurance in each of the last five years [Data version 2026-11-11.13378f]. Retrieved November 11, 2026, from https://polisapro.com/insights/underwriting-profit-five-years
BibTeXShow entry
@misc{polisa_insights_underwriting_profit_five_years_2026,
  author       = {{Polisa}},
  title        = {40 of 64 large non-life insurers in the EU markets made an underwriting profit after reinsurance in each of the last five years},
  year         = {2026},
  version      = {2026-11-11.13378f},
  howpublished = {\url{https://polisapro.com/insights/underwriting-profit-five-years}},
  note         = {Accessed 11 November 2026}
}
Reuse: Polisa's compilation CC BY 4.0 · source data under each publisher's terms, see Method.